PART 1
After my husband passed away four winters ago, my son Greg convinced me I couldn’t leave my life insurance payout sitting in a regular checking account.
“Mom, inflation will eat thirty percent of that money before you turn seventy,” Greg told me over a cold cup of coffee at my kitchen table. “You need someone who knows the market.
Mr. Easton handles all the families at church. He does the youth pastor’s retirement, and he handles the fellowship hall endowment. He’s safe.”
Mr. Easton had an office two doors down from the town square pharmacy, with dark wood paneling, a brass coat rack, and framed scripture prints on the cream walls. He had silver hair, a soft handshake, and an easy smile that made you feel like you were sitting with a favorite deacon. He told me high-yield municipal and utility bonds were the smartest place for a widow on a fixed widow’s pension.
“We want steady, quiet growth, Mrs. Gable,” he said that first morning. “You give me six hundred dollars a month out of your survivor benefit, plus your initial deposit, and we will build a fortress around you.”
So every single month for four years, I wrote a check for six hundred dollars, walked it into his office, and handed it to his receptionist.
Every quarter, a white envelope with blue lettering arrived in my mailbox.
The statements were printed on heavy bond paper with little pie charts showing my portfolio climbing. By the end of this past September, the bottom line on Mr. Easton’s official quarterly statement showed a total balance of $58,000.
To most people, fifty-eight thousand dollars sounds like a tidy sum.
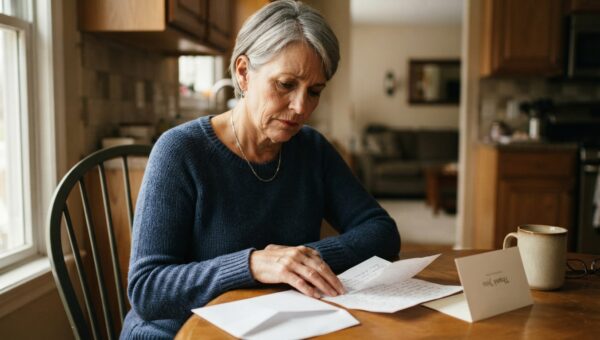
But I am old-fashioned. My mother worked thirty-two years behind the counter at the county water department, and she taught me that a person does not trust another person’s math when their own roof is on the line. I keep a stiff, cloth-bound green ledger in the bottom drawer of my secretary desk, right next to the receipt box. Every deposit, every check number, and every monthly draft gets recorded with a black ballpoint pen.
On a rainy Thursday night, I sat down under the dining room lamp with my reading glasses and an adding machine.
I totaled my green ledger entries once. Then I cleared the tape and ran them a second time.
Then I went line by line, comparing each check carbon against my bank statements, and ran them a third time.
By Mr. Easton’s statements, my total investment was worth $58,000.
By my green ledger, I had handed his office exactly $74,000 in cash drafts over four years.
That was sixteen thousand dollars gone before you even counted a single dollar of the four percent annual interest he had promised me in writing. The numbers would not meet. Even if every utility bond in the state had dropped in value, the principal deposits alone did not add up. Sixteen thousand dollars had simply vanished into thin air.
I didn’t sleep that night. At eight-thirty the next morning, I put on my wool coat, tucked my green ledger into my canvas bag, and drove down to the square.
The receptionist was on the phone, but Mr. Easton’s office door was open. When he saw me, he stood up, smoothing his gray necktie, and gave me that warm church smile.
“Mrs. Gable,” he said, holding his hand out toward the leather armchair. “What brings you out on such a wet morning?”
I didn’t sit down. I walked to his heavy mahogany desk, unzipped my bag, and laid the green ledger flat against the blotter.
“I spent last night adding up my payments, Mr. Easton,” I said. “Your statement says fifty-eight thousand. My checks show seventy-four thousand.”
His smile stayed in place, but his eyes moved quickly from the green cloth cover to my face. He laughed, a quiet, friendly chuckle.
“These things get complicated, dear,” he said, reaching for a pen. “Between management loads, municipal bond call dates, and quarterly yield spreads, paper accounting can look confusing to folks who aren’t in the trade.”
I reached over, flipped the ledger directly to the page marked with a red paperclip, and tapped the column with my index finger.
“Then explain this line, Mr. Easton,” I said. “The one where six thousand dollars of my principal was transferred out to an account called G.M. Consulting.”
PART 2
The room went so quiet that the grandfather clock in the corner sounded like a hammer hitting wood.
Mr. Easton did not touch the ledger. His silver pen hovered half an inch above the blotter, then he set it down on a brass tray without making a click.
“Mrs. Gable,” he said, his voice dropping into that soothing, pastoral cadence he used after Sunday services. “That was an authorized allocation. When we set up your portfolio, your son Greg signed as your secondary family representative. G.M. Consulting is a private commercial property fund Greg operates. He requested a short-term liquidity loan against your bond reserves to secure an equipment purchase for his business.”
My stomach tightened into a knot so hard it made breathing difficult.
“Greg doesn’t run a commercial property fund,” I told him, looking straight into his eyes. “Greg works for an asphalt contractor in town. And Greg does not own my money.”
“He presented a signed power of attorney rider,” Mr. Easton said. He opened his desk drawer, pulled out a thin legal folder, and turned a single page toward me.
There was my signature at the bottom of a financial authorization form. The date at the top was three years ago, during the week of my hip surgery when Greg had brought me a stack of insurance claim forms while I was still groggy from anesthesia in the rehabilitation wing. He had told me they were Medicare copay waivers.
Beside my signature was Greg’s full legal name: Gregory Mark Gable.
And written in the memo line for the six-thousand-dollar transfer was the name of a business entity Greg had registered using his home address on Maple Street.
I turned the page in my green ledger.
“That six thousand was just the first one, wasn’t it?” I asked.
Mr. Easton leaned back in his leather chair. The friendly deacon demeanor was gone. His shoulders tightened, and his expression turned cold and guarded.
“Your son assured me you were fully aware of the family arrangement, Mrs. Gable. Over the last three years, Greg has drawn sixteen thousand dollars in secondary loans against your cash yields. He signed promissory notes for every dollar. It is all documented. He is your son. I had no reason to question a family matter.”
“You had seventy-four thousand reasons,” I said. “You took six hundred dollars out of my survivor check every thirty days. You printed statements that hid his withdrawals by showing a fake balance so I wouldn’t ask why my savings were shrinking. You covered for him because you didn’t want to lose the church account.”
Mr. Easton stood up from his desk. He reached across and closed my green ledger with both hands.
“I suggest you go home and talk to your son, Mrs. Gable,” he said, his voice clipped and quiet. “This is an internal family dispute. If you choose to make a public scene out of this, it will involve legal fees that will wipe out whatever balance you have left. Go home. Talk to Greg. Let him pay back the promissory note privately.”
I didn’t answer him. I picked up my ledger, pulled it tight against my coat, and walked out the door into the rain.
I didn’t drive home. I drove two miles across town to the asphalt contractor’s yard where Greg worked as an equipment dispatcher.
The yard smelled like hot tar and diesel exhaust. I walked into the dispatch trailer with my green ledger in one hand and my car keys in the other. Greg was sitting behind a laminate desk with two radio headsets on, eating a glazed doughnut.
When he looked up and saw me standing in the doorway of a work shack in the middle of a Friday morning, the doughnut stopped halfway to his mouth.
“Mom?” he asked, pulling the headset down around his neck. “What are you doing out here? Did something happen to your car?”
I set the green ledger squarely on the grease-stained counter between his dispatch radio and his coffee mug.
“I just came from Mr. Easton’s office, Greg,” I said plainly. “We need to talk about G.M. Consulting.”
PART 3
Greg’s face lost all its color. He looked quickly at the two truck drivers sitting on a bench near the door, then pushed his chair back and grabbed my elbow, steering me into a small storage room stacked with spare oil filters and paper road maps.
He shut the hollow-core door behind us.
“Mom, keep your voice down,” he whispered, running a hand through his hair. “Why did you go to Easton’s office? I told you I was handling all of that.”
“You handled sixteen thousand dollars of my pension money straight into your pocket,” I said. “You had me sign a power of attorney while I was lying in a hospital bed with a broken hip. How could you do that to your own mother?”
Greg didn’t look at the floor. He leaned back against a metal shelf, and an ugly, bitter look crossed his face.
“Do you have any idea what it costs to live right now?” he hissed, keeping his voice low through his teeth. “Karen’s car got repossessed in twenty-twenty-two. The kids needed braces. I was twelve thousand dollars behind on our mortgage because the county cut back on road paving contracts. Dad left you the house completely paid off, and he left you thirty-six hundred a month in pension checks! You don’t spend eight hundred dollars a month on yourself! You sit in that house watching the birds and saving money for nobody!”
“That money was your father’s life,” I told him, my voice shaking. “He worked forty years on high-voltage lines in the ice and sleet so I wouldn’t have to beg anybody for bread when he was gone. He worked so I could pay my own taxes and keep my own dignity. And you stole it.”
“I didn’t steal it!” Greg snapped. “I borrowed it against my inheritance! You’re seventy-one years old, Mom. When you pass, that money comes to me anyway! I just took an advance when my family was drowning so my kids wouldn’t lose their bedrooms.”
“It wasn’t your inheritance, Greg,” I said. “It was my life.”
He stepped closer to me, his voice harsh. “If you go to the police, Easton loses his license, the church gets dragged through the dirt, and I go to jail. If I go to jail, Karen and the kids are on the street. Is that what you want? To put your own grandchildren out of their house over sixteen thousand dollars you weren’t even spending?”
I stood there in that dim room surrounded by the smell of machine oil. I looked at the boy I had carried, the boy whose fevers I had tended, the boy who had stood at his father’s grave and promised to look after me.
He didn’t look like my son. He looked like a stranger who had decided I was already dead and gone.
“You have thirty days, Greg,” I said.
“Thirty days for what?” he asked, his jaw tight.
“Thirty days to secure a home equity loan on your house and wire every single penny of that sixteen thousand dollars back into my personal bank account at First State Bank,” I said. “Not through Easton. Not through a bond fund. Directly to my account.”
Greg let out a short, mocking laugh. “And if I can’t? The bank won’t approve me for that much equity without higher income. You know my credit is shot.”
I reached into my purse, pulled out the carbon copy of the G.M. Consulting transfer slip Easton had handed me, and held it up.
“If the money is not in my account by November fifteenth,” I told him, “this document, along with my hospital admission records showing I was under narcotic pain medication the day you had me sign that rider, goes to the county prosecutor and the state securities commissioner. And then I will walk across the street and hand a copy to the pastor at church.”
Greg stared at the paper. The sneer disappeared from his mouth.
“You wouldn’t do that to me,” he whispered. “You’re my mother.”
“Your mother died the second you decided she was just a bank account,” I said.
I picked up my green ledger from the counter, walked out past the truck drivers, and got back into my car.
ENDING
The money did not come from a bank loan.
Two weeks later, Greg and his wife Karen put their bass boat, their riding mower, and their camper up for sale on the town buy-and-sell board. On November tenth, a cashier’s check for $16,000 arrived at my house by certified mail. There was no letter inside. There was no apology card. Just the bank draft made out to Ruth Gable.
The next morning, I drove down to First State Bank. I opened a private certificate of deposit in my name alone, with no secondary beneficiaries and no power of attorney attached. I deposited the sixteen thousand dollars. Then I went to Mr. Easton’s office, closed my remaining investment account, and took the remaining $58,000 out in a single certified bank check, moving every cent of my savings to the local bank where my father had kept his money fifty years ago.
Mr. Easton tried to hand me a release form absolving his brokerage of liability. I refused to sign it. I told him if he ever spoke my name at Sunday service again, I would hire an attorney from the county seat to audit every church endowment fund he managed. He did not say a word. He just handed me my check and looked at the floor.
Thanksgiving was quiet this year.
Greg did not call. Karen did not bring the grandchildren by with pumpkin bread like she usually did. My sister drove over from Canton, and the two of us roasted a small turkey breast, ate mashed potatoes, and watched old home movies of our parents camping in the Smokies.
It hurt. I would be lying if I said there weren’t nights when I sat in my living room with the television off, listening to the floorboards creak, wondering if I should have just kept my mouth shut and let him have the money. A mother’s heart is a stubborn, foolish thing. It wants to protect her children even when they are the ones holding the knife.
But then I think about my husband, Arthur. I think about him getting up at four in the morning in the middle of January, pulling on two pairs of wool socks, and heading out into the freezing wind to keep the power lines clear so his family would have a roof over their heads. He didn’t break his back for forty years so our son could treat his mother like an inconvenient obstacle to an inheritance.
Yesterday morning, my monthly survivor pension cleared into my checking account.
I sat down at my secretary desk by the window. I opened my green cloth ledger to a fresh, clean page. With my black ballpoint pen, I wrote down the date, the exact deposit amount, and the new balance down to the penny.
The numbers lined up straight and true. I closed the book, put the cap on my pen, and put the ledger back in the drawer where it belongs.