PART 1
My brother put a sale agreement beside the change machine at our laundromat and told me I had until Friday to sign it. Dad had been dead four years, but the place still smelled like the lemon soap he used to mop the floors, and I could not make myself treat it like a number on a page.
“I’m not signing,” I said.
Mark leaned on the folding table. He was sixty-one, three years older than me, and looked more tired than angry. “Then tell me how we pay the loan. The buyer is offering enough to clear it and leave us both something.”
He said the business was failing. He said our regulars were dwindling and the machines were too old to keep patching. He’d already spoken to a buyer who wanted the building for storage units. My brother had run the books since Dad’s stroke. I handled the counter, the wash-and-fold orders, and the weekly delivery to Birch House, a senior residence that had used us for years.
I believed the shop was struggling. I didn’t believe it was as bad as Mark claimed. Every Thursday, I counted the Birch House bags myself. Every month, I watched their payment arrive. So when Mark said we were nearly three months behind on the business loan, I asked to see the statements.
He said he’d left them at home.
That night, after the last customer left, I opened the drawer where Dad used to keep appliance manuals. Behind the warranty papers was a green ledger. His handwriting filled the first half; Mark’s filled the rest. Dad had used it to track cash jobs before we switched to a computer system. I found three Birch House payments marked as received, each with a date and check number. The digital report Mark had printed for me showed only two.
The next morning, I called Birch House’s bookkeeper. She confirmed all three checks had cleared. Then I called the bank and asked for copies of the loan payments. I had authority to request them as a co-owner, though Mark had made most of the calls.
The statements came by email that afternoon. A monthly transfer went from the business account to a storage company across town.
The description said “equipment.” We owned no equipment in storage. I drove there before closing and saw Mark’s old delivery van through the open bay door. Beside it were three commercial washers still wrapped in plastic.
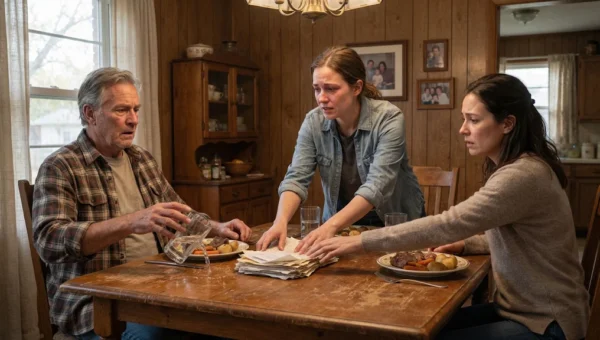
When Mark came in that evening, I put the ledger and statements on the counter.
He stared at the storage line. “You went looking through my things?”
“Through Dad’s ledger. The Birch House money came in. Where did it go?”
He sat down hard. For a moment, I thought he might lie. Instead, he rubbed his face and said the washers were for a second location he’d planned to open. He’d borrowed against the business to buy them. The lease fell through, and the lender was still charging him. He’d kept making payments from our account and told himself he’d replace the money when he sold the machines.
“You let me think the shop was dying,” I said.
“I was trying to keep it alive until I could fix it.”
His voice cracked on the last word. He told me his daughter’s tuition was due, his divorce payments had gone up, and the second-location loan was personally guaranteed by both of us. He had not taken the money for a vacation. That didn’t make it ours to spend without asking.
I looked at the wrapped washers in the photograph he showed me. They might sell, but not quickly enough to meet the bank’s deadline. The buyer’s offer would cover the debt. If I refused, our machines and the shop itself could be at risk. If I signed, Birch House would have to find another laundry, and the three women who worked mornings with me would lose their jobs.
I called the buyer and said I would consider a sale only if the offer included time for us to notify our customers and help the staff find work. He said he needed an answer by Friday. Then I called Birch House and asked whether they’d stay with us if we made a payment plan. Their administrator said she would, but needed to know whether we could keep the washers running.
At closing, Mark waited by the front door while I turned the key in the office lock. He looked smaller than he had that morning.
“I’m not asking you to trust me,” he said. “Just don’t let the bank take Dad’s place before I can explain what else I signed.”
My phone rang. The bank officer said a document had arrived that afternoon with my name on it, and asked whether Mark was standing beside me.
PART 2
I told the bank officer I was alone, though Mark was twenty feet away by the glass door. She asked if I had signed a secondary agreement authorizing an equity line on the building itself. I told her I hadn’t signed anything since Dad’s estate settled four years ago.
She paused on the line, the kind of professional silence that makes your stomach drop. Then she said a notary public had witnessed my signature six months prior, using a driver’s license number that matched my old state ID.
I hung up without answering.
Mark was watching me from the dark sidewalk through the plate glass, his hands shoved deep into his jacket pockets. He didn’t knock, and he didn’t drive away. He just stood there under the yellow glow of the streetlamp like he was waiting for the verdict.
I walked over and unlocked the door. I didn’t yell. When you find out someone has forged your name to borrow against everything your father built, yelling feels too small.
“The bank called,” I said.
Mark didn’t look up from the concrete. “I had to, Sarah. The first loan was going into default. If they foreclosed on the commercial mortgage, we would have lost the house and the shop both. The equity line was the only way to cover the arrears.”
“You signed my name.”
“I had power of attorney when Dad was sick. I just used the same form.”
“That power expired the day probate closed, Mark, and you damn well know it.”
He finally looked at me, his eyes bloodshot and defensive. “What else was I supposed to do? Let the marshals padlock the doors while you’re folding towels for Birch House? At least this way we have time.”
We had time, but we didn’t have a business anymore. I walked back inside, past the rows of front-loaders that had hummed through my entire childhood, and sat at Dad’s old wooden desk. The green ledger was still open where I left it. Beside it was the sale agreement Mark wanted me to sign by Friday.
I spent the next two hours going through every drawer in that office. If he had forged one document, there were others. I found a second file tucked behind the spare receipt rolls. It wasn’t bank statements this time. It was a notice of default from a commercial lender in the city, dated three weeks ago, naming both Mark and me as defendants on a sixty-thousand-dollar judgment.
He hadn’t just borrowed against the shop. He had used the building as collateral for a private loan to settle his divorce lawyer’s retainer.
PART 3
The next morning, I called Arthur Vance. He was an attorney in town who had handled Dad’s will and knew every brick in our commercial district. He didn’t tell me what I wanted to hear. He told me the forged equity line was a criminal matter, but if I reported it, the bank would immediately accelerate the entire debt, and the building would go straight to a sheriff’s auction.
“Your brother put you in a corner,” Arthur said over his desk glasses. “You can save your credit and your half of the property by forcing a partition sale, but the laundromat closes either way. Or you can cover his default, take full title to the building yourself, and leave him out of the title entirely.”
“Can he do that legally? Borrow against my inheritance without my consent?”
“No,” Arthur said quietly. “He committed fraud. But families usually try to solve these things in the kitchen before they solve them in a courtroom. The question is whether you want to pay his debts or let the place go.”
I went back to the laundromat at noon. The morning shift was finishing up. Brenda, who had worked our registers for twelve years, was folding a basket of heavy flannel sheets from Birch House. She asked if the rumors about the storage company were true.
“We’re working on it,” I told her, my voice steadier than my hands.
Mark was there, sitting on a folding chair by the soap dispensers, waiting for me. He looked like he hadn’t slept at all. He had a cashier’s check for five hundred dollars in his hand, his share of the week’s cash drawer.
“Arthur called me,” Mark said before I could sit down.
“You talked to him?”
“I called him from my car. I told him I signed your name. I told him you didn’t know anything about the second loan.” Mark stood up, letting the cashier’s check flutter onto the counter. “Sign the sale agreement, Sarah. The buyer’s deposit will cover the second loan and the bank arrears. We walk away clean. We split whatever is left.”
“And Brenda?” I asked. “And the Birch House contract?”
“They’ll find another place. Everything closes down eventually.”
I looked at the green ledger Dad had left behind. On the first page, in his neat, slow handwriting, he had written the rule he lived by: *A business is only as honest as the person holding the keys.*
“No,” I said.
“Sarah, be reasonable—”
“I am being reasonable. You’re going to sign a quitclaim deed transferring your half of the property to me. In exchange, I’ll assume the primary mortgage and pay off the small bank debt you ran up for your truck. But the second loan, the one you forged my signature on? That’s yours. You deal with them.”
He stared at me like I had spoken a foreign language. “You can’t do that. I’m a co-owner.”
“You were a co-owner until you committed forgery to steal my equity,” I said. “Arthur has the affidavit ready. You sign the deed by four o’clock today, or I hand the bank’s fraud packet to the district attorney.”
ENDING
Mark didn’t sign at four. He signed at five minutes to five, sitting right at the front counter while the evening regulars came in with their plastic baskets of laundry. His hand shook so badly he had to press the pen twice to make his middle name legible.
When he finished, he didn’t look at me. He picked up his jacket from the plastic chair, walked out the front door, and got into his van without looking back.
The shop is mine now. The bank adjusted the mortgage terms after Arthur showed them the transfer, and Birch House renewed their contract for another three years. The three women who work the morning shift are still behind the counter, and the lemon soap still smells the same when I mop the floors after closing.
Last night, I found an old receipt tucked inside the back cover of Dad’s ledger. It was from thirty years ago, for a replacement belt on the large front-loader by the window. Mark’s name was written at the bottom in pencil, where he had helped his father fix the belt before school.
I folded the receipt and put it back where it belonged, then turned off the front lights and locked the door by myself.