PART 1
I never thought my own mother would look me in the eye and tell me my grief made my daughter worth less than her cousins.
My husband, Mark, died four years ago when our daughter, Lily, was only eight. He had an aggressive lymphoma that took him in under six months. Mark was a planner, the kind of man who kept color-coded folders in a fireproof safe in our basement.
Before he passed, he set aside ninety-two thousand dollars specifically for Lily’s future. It was supposed to sit untouchable in a dedicated trust until she turned eighteen, meant to pay for her college tuition, her books, and whatever start in life he knew he wouldn’t be around to provide.
Because I was utterly shattered back then, barely able to get out of bed or remember to pack Lily’s lunch, my father offered to help manage the administrative setup. He had worked as an office manager for an auto parts distributor for thirty years. He always acted like he was the only person in the family who understood banking, paperwork, and legal filings. Mark had named my father as the secondary trustee alongside me, simply as an emergency precaution in case something happened to both of us. Mark trusted him. I trusted him.
That trust ended on a Tuesday afternoon three months ago.
I had logged into the local credit union where the trust was housed to print out the quarterly statement for Lily’s annual tax filing.
When the account screen loaded, my stomach dropped. The balance did not say ninety-two thousand dollars plus interest. It read four hundred and twelve dollars and sixteen cents.
I sat there staring at the screen, convinced it was a technical glitch or some terrible fraud. I called the branch immediately. The teller was polite, but after checking the history, she told me the truth. A cashier’s check for ninety-one thousand eight hundred dollars had been drawn against the trust account two weeks earlier. The transaction had been executed in person by my father, using his authorized trustee status and presenting what the system listed as an updated legal instrument and withdrawal authorization.
I drove straight to my parents’ house. My hands were shaking so hard on the steering wheel that I nearly missed the turn onto their street. Lily was in the passenger seat. She had come home from school with a slight fever, and I had picked her up an hour early.
I told her to wait in the car with the air conditioning running, but as soon as I opened the front door, she must have slipped out behind me to grab her backpack from the porch.
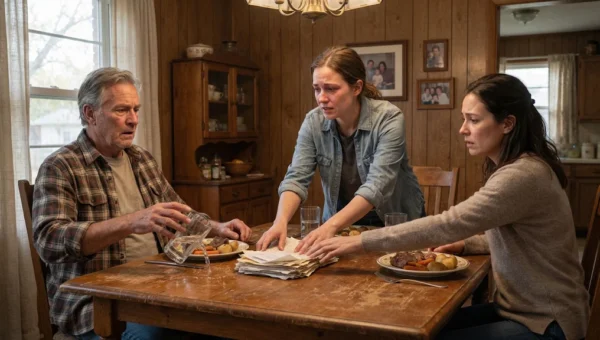
My mother was standing at the kitchen island, folding dish towels. My father was at the kitchen table, looking over a stack of glossy home improvement brochures.
When I laid the printed statement on the counter and asked where Mark’s money was, my father didn’t even flinch. He took off his reading glasses, set them down, and looked at me like I was a difficult customer at his old job.
“We took care of a family emergency, Sarah,” he said, his voice flat and practical. “You don’t need to make a scene.”
“That is not family emergency money,” I said, my voice cracking. “That is Mark’s life insurance payout for Lily. That is her college fund. Where is it?”
My mother threw down the dish towel she was holding. She didn’t look guilty. She looked annoyed that I was questioning them.
“We paid off Amanda’s mortgage balloon payment,” my mother said coldly. “The lender was going to foreclose on their house at the end of the month. Tom’s hours were cut at the plant, and Amanda was having panic attacks. She has three children to raise, Sarah. Three mouths to feed. You have just one.”
The words hit me like physical blows. I stood there in the kitchen where I grew up, listening to my mother tell me that because Mark died and left me with an only child, my daughter was only entitled to a fraction of the family’s concern.
“You stole from a dead man,” I whispered. “You stole from an orphaned twelve-year-old girl.”
“Mark would have wanted his family protected,” my father snapped, standing up to loom over me. “Amanda was about to be out on the street with your nieces and nephew. You have your job, you have the house Mark paid off, and you have social security survivors benefits coming in every month. You are comfortable. Amanda is drowning. We made a executive family decision. When Amanda and Tom get back on their feet in a few years, they will pay it back into the fund.”
“They don’t have ninety thousand dollars, Dad! They have never paid back a single dime they borrowed from anyone!”
“That is enough!” my mother barked. “Amanda has three children. You have just one. Stop being so selfish. A good mother would understand what family sacrifice looks like.”
A soft rustle came from the hallway doorway.
I turned around. Lily was standing there against the doorframe, clutching her navy school backpack against her chest. Her face was completely pale. Her dark eyes, the exact same shape and color as Mark’s, looked right at my parents, then up at me.
She had heard every single word.
I expected her to burst into tears or run back to the car. Instead, Lily walked forward two steps, looked directly at my mother, and asked in a quiet, trembling voice, “Was that money really meant for me? Did Dad leave it for me, or was it Grandma’s?”
My mother’s expression tightened, but she didn’t soften. “Lily, go wait outside. Grown-ups are talking.”
“No,” Lily said. She didn’t shout. Her voice had an unnatural, steady calm that made my heart break into pieces. “I want to know if Dad wanted Aunt Amanda to have it.”
My father looked away, suddenly finding the wood grain of the dining table very interesting. My mother crossed her arms and looked out the window. Neither of them had the courage to answer a twelve-year-old girl to her face.
I took Lily’s hand. Her fingers were ice cold.
“Come on, sweetie,” I said, turning my back on my parents. “We’re leaving.”
“Sarah, don’t you dare walk out of here and cause a rift over money,” my mother yelled after me as we reached the foyer. “Family comes first! You remember that!”
I walked out the front door, locked Lily into the car, and pulled away from the curb. My hands were no longer shaking. The panic had burned off entirely, replaced by a cold, clear fury I had never felt in my entire life. They hadn’t just moved numbers on a ledger. They had taken the last tangible gift my dying husband had left for our little girl, treated it like their personal emergency slush fund, and told her to her face that she mattered less than her cousins.
PART 2
I didn’t drive home. Instead, I pulled into an empty church parking lot three miles down the road, put the car in park, and pulled out my phone.
I called Arthur Vance. Arthur had been Mark’s friend since college, but more importantly, he was the estate attorney who had drafted the original trust agreement in his office downtown while Mark was undergoing chemotherapy.
Arthur’s secretary told me he was between client meetings, but the moment I told her what had happened, Arthur picked up the line.
“Sarah? What’s going on?” he asked.
“Arthur, Dad took the ninety-two thousand out of Lily’s trust,” I said. “The credit union gave him a cashier’s check. He paid off Amanda’s mortgage. He said he had the legal right as secondary trustee.”
There was complete silence on the other end of the line for three full seconds. When Arthur spoke again, his voice was dangerously level. “Bring Lily and come to my office right now. Bring your original physical copy of the trust binder Mark kept in the safe.”
An hour later, Lily and I were sitting across from Arthur in his wood-paneled conference room. Lily was curled up in a leather armchair with a pad of paper and a pen Arthur had given her, quietly drawing pictures of our dog. Arthur was reading through the original, notarized trust agreement Mark had signed four years prior.
He flipped to page six, ran his index finger down the paragraphs, and stopped. He stared at a single page for a long time. Then he leaned back in his chair, pulled off his wire-rimmed glasses, and let out a slow breath.
“Your father was listed as a contingent successor trustee, Sarah,” Arthur said carefully. “He only had administrative signing authority in the event that you were medically incapacitated or deceased. In order for him to withdraw even five dollars from this principal without your signature, he would have had to present either a certified death certificate for you or a signed medical power of attorney declaring you incompetent.”
“He didn’t have either of those,” I said. “I’m alive. I’m right here.”
“Then he couldn’t have used this trust agreement,” Arthur said.
Arthur picked up his desk phone, dialed an internal extension, and asked his paralegal to pull the electronic filing records from the county probate court and contact the fraud compliance division at First Heritage Credit Union. While we waited, Arthur looked across the table at Lily, who was still drawing quietly.
“Your dad loved you more than anything in this world, Lily,” Arthur said gently. “Every single dollar in that fund was put there specifically for your education. No one had the right to touch it. And we are going to fix this.”
Lily looked up from her drawing. “Grandma said Aunt Amanda has three kids, so they needed it more.”
“Your grandmother is wrong,” Arthur said firmly. “The law doesn’t care how many children someone has. That money belonged to you, protected by your father’s signature.”
Ten minutes later, the fax machine in the corner chimed and printed three pages from First Heritage’s compliance office. They had transmitted the withdrawal packet my father had submitted to the branch manager two weeks earlier.
Arthur picked up the pages. As he scanned the second sheet, his eyes widened slightly. He picked up his desk phone again and dialed a direct number.
“David? It’s Arthur Vance,” he said. He spoke in short, clipped sentences. “I have a major fraudulent conveyance on an irrevocable testamentary trust. The credit union accepted an altered trustee amendment. It bears my firm’s letterhead, but the notary stamp is from a mobile notary in county jurisdiction, and my signature is a crude cut-and-paste forgery from a 2021 probate filing. The funds were wired directly to a title escrow company to satisfy a mortgage lien.”
Arthur listened for a minute, nodding slowly.
“Yes,” Arthur said. “I’m sending the original execution copies over right now. The beneficiary is a minor. The actual executor is sitting in my office.”
He hung up the phone and looked directly at me. His face was entirely devoid of sympathy now; it was pure legal steel.
“Sarah, listen to me very carefully,” Arthur said. “Keep this from your parents. Do not call your mother. Do not text your sister. Do not confront your father again. Do not demand the money back. Do not tell them we pulled these documents.”
“Arthur, why?” I pleaded. “They literally handed stolen money to Amanda’s mortgage company! We have to stop it!”
“The wire already cleared two weeks ago, Sarah,” Arthur explained calmly. “The lien release has already been filed with the county recorder. If you alert them now, your sister and brother-in-law will attempt to transfer the deed, take out an equity line, or hide assets. More importantly, your father committed multiple felonies. He forged an attorney’s signature, altered a legal trust instrument, and defrauded a federally insured financial institution to move ninety-one thousand eight hundred dollars. The credit union’s internal security team and the regional bank fraud division are taking over the investigation immediately.”
“What about Lily’s money?”
“The credit union is legally liable for releasing funds on a forged document without verifying the primary trustee,” Arthur said. “First Heritage will have to make Lily’s trust whole out of their own insurance reserves. But the bank will not take that ninety-two thousand dollar loss quietly. They will pursue the recipient of the funds to recover every single cent.”
He leaned forward, tapping his desk. “Six weeks. The bank’s forensic audit and the county prosecutor’s review will take about six weeks to finalize the paperwork and secure the recovery warrants. During those six weeks, you act completely normal. If they call you, be quiet. Do not let them know the trap is already closing.”
I looked down at Lily. She was watching me, waiting to see what I would do.
“We stay quiet,” I whispered.
PART 3
For the next month and a half, staying silent was the hardest thing I had ever done.
My parents took my silence as surrender. My mother sent a couple of breezy text messages about family dinners, which I politely declined, claiming Lily was busy with soccer practice and school projects. Amanda didn’t call me once. She didn’t offer an apology, she didn’t offer a thank you, and she didn’t check on Lily. She simply absorbed the ninety-two thousand dollars as if it were her birthright.
Then, six weeks after my visit to Arthur’s office, my mother sent a mass family group text.
She was throwing a Sunday afternoon backyard barbecue at Amanda’s house to celebrate Amanda and Tom becoming “officially mortgage-free.” The text was full of exclamation points and celebratory emojis, praising Amanda’s resilience and talking about how “blessed” the family was to overcome financial hardship through “mutual support.”
My mother even sent a private follow-up text to me: *Sarah, put the past behind you and bring Lily. Amanda wants to see her nieces and nephew all together. It’s time for you to show your sister some grace.*
I showed the message to Arthur.
“Go,” Arthur told me over the phone. “The bank’s regional fraud investigator, Marcus Thorne, received the recovery writ from the district judge on Friday afternoon. The title company and the county sheriff have already served the administrative notices to the county registry this morning. Thorne told me he intends to deliver the demand for restitution and the rescission order in person today before filing the formal criminal complaint. You should be there.”
I didn’t take Lily. I left her at a friend’s house for a movie afternoon. This was not something she needed to witness.
When I arrived at Amanda’s split-level suburban home at two in the afternoon, the driveway was packed with cars. Music was playing from speakers on the back patio. The smell of grilled hamburgers filled the air. My father was standing by the grill in an apron, holding a beer and laughing with Tom. My mother was carrying a tray of iced tea out to the patio table, surrounded by neighbors, church friends, and Amanda’s in-laws.
Amanda was in the center of the yard, wearing a bright yellow sundress. She had a framed document sitting on the outdoor picnic table—a ceremonial printout from the mortgage servicer showing a zero-dollar balance.
When my mother spotted me walking through the side gate, her face lit up with smug triumph. She honestly thought I had come to bend the knee and accept her hierarchy.
“Look who decided to join the family!” my mother announced loudly, drawing the attention of the thirty guests milling around the lawn. “Sarah, come have a drink. Amanda, your sister came after all!”
Amanda walked over, holding a glass of wine. She offered me a tight, condescending smile. “I’m glad you came, Sarah. I know things were tense, but Mom explained everything. Honestly, once Tom’s promotion comes through next year, we’ll talk about putting some money back into a fund for Lily. Family takes care of family, right?”
She said it with such casual disregard, as if stealing my daughter’s future was nothing more than borrowing a cup of sugar.
Before I could say a single word, the side gate clicked open again.
A tall man in a dark charcoal suit walked into the backyard, accompanied by a uniformed county sheriff’s deputy. The man carried a thick manila folder and a leather briefcase.
The patio music suddenly felt very loud. Tom stepped away from the grill and lowered the volume on the portable speaker.
“Can I help you folks?” Tom asked, wiping his hands on a kitchen towel. “This is a private family party.”
The man in the suit stopped near the patio table, right beside Amanda’s framed mortgage statement. He didn’t look angry; he had the clinical, professional detachment of an auditor who had seen this exact scenario a hundred times before.
“My name is Marcus Thorne,” the man said clearly, his voice carrying across the silent yard. “I am the senior fraud investigator for First Heritage Credit Union, appearing on behalf of the institution and the county chancery court. Is Thomas and Amanda Miller present?”
Amanda blinked, her smile vanishing. “I’m Amanda Miller. What is this about?”
“And are Robert and Eleanor Hayes present?” Thorne continued, looking toward my parents.
My father set his beer bottle down on the patio table. His face had gone completely gray. “I’m Robert Hayes. What’s the meaning of this?”
Mr. Thorne opened his folder and pulled out a stack of documents.
“Mr. Hayes, on September 14th of this year, you presented an altered and forged trust instrument to First Heritage Credit Union, unauthorized by primary trustee Sarah Hayes or the legal estate of Mark Hayes. You withdrew ninety-one thousand eight hundred dollars from the minor testamentary trust of Lily Hayes and directed those funds via bank wire to ClearTitle Escrow to satisfy loan account number 8841, registered to Thomas and Amanda Miller.”
A collective gasp rippled through the neighbors and friends standing around the yard. Tom’s parents looked at each other in absolute horror.
“Now wait just a minute!” my father stammered, taking a step forward. “I was a trustee! I had the authority to manage those family funds! It was an internal family loan!”
“You were a contingent trustee with zero withdrawal authority without proof of Sarah Hayes’s death or total medical incapacitation,” Mr. Thorne replied, his voice cutting through my father’s bluster like a scalpel. “To bypass that restriction, you submitted a forged document bearing the fabricated signature of attorney Arthur Vance and an illicitly obtained notary seal. That is bank fraud under federal statute, and grand larceny under state law.”
My mother rushed forward, her voice shrill. “This is a private family matter! Sarah gave permission! She’s standing right there! Tell him, Sarah!”
Everyone turned to look at me.
“I never gave permission,” I said clearly, looking directly into my mother’s eyes. “You took Mark’s money out of Lily’s hands while her father is in a cemetery. You told me my daughter didn’t matter because Amanda had three kids and I only had one.”
Whispers broke out among the guests. Two of Amanda’s church friends immediately set their paper plates down on a patio chair and quietly slipped toward the side gate.
“The credit union has already restored the full ninety-two thousand dollars to Lily Hayes’s trust account under our institutional insurance coverage,” Mr. Thorne announced, turning his attention to Amanda and Tom. “However, because the funds used to satisfy your mortgage lien were directly traced proceeds of criminal fraud and grand theft, the transaction has been judicially vacated.”
Amanda’s hand began to shake, spilling red wine onto the grass. “What does that mean? What do you mean vacated?”
“It means your mortgage was not legally satisfied,” Mr. Thorne said. He pulled a court order from the folder and handed it directly to Tom. “The chancery court has issued a lis pendens and an immediate restitution lien. First Heritage has stepped into the shoes of your original lender. Because your mortgage maturity date expired on the first of this month without legitimate funds being provided, the foreclosure process has been formally reinstated.”
“No,” Tom choked out, his voice cracking. “No, we have a clear title! We have the letter!”
“You have a letter obtained with stolen money,” the deputy sheriff standing beside Thorne stated plainly. “Mr. Miller, Mrs. Miller, you have thirty days to produce ninety-one thousand eight hundred dollars in certified funds to First Heritage, or the property will be scheduled for a sheriff’s auction next month. Furthermore, Mr. Robert Hayes, you are being served with a formal summons to appear before the county grand jury on felony fraud charges.”
The deputy handed a thick packet of court summons directly into my father’s limp hands.
ENDING
My mother completely collapsed into a patio chair, sobbing hysterically and screaming that I had destroyed the family. Amanda dropped her wine glass on the concrete, shattering it into pieces, and turned on my father, screaming at him for telling her the money was “clean and legally handled.”
Tom stood staring at the paperwork in his hands, completely unable to look at his own parents, who were already walking toward their car in profound embarrassment.
I didn’t stay to watch the rest of the collapse. I turned around, walked out the side gate, and drove away.
The consequences were swift, ugly, and entirely of their own making.
Amanda and Tom couldn’t raise ninety thousand dollars in thirty days. No legitimate bank would touch them with an active fraud investigation attached to their title history. They were forced to sell the house in a distressed, hurried sale just to pay off the reinstated lender balance and legal fees. They ended up moving into a cramped, two-bedroom rental apartment on the far side of town. Tom’s family was so disgusted by the revelation that they refused to lend them a single penny.
My father was formally indicted three months later. Because of his age and lack of prior criminal history, Arthur Vance and the prosecutor worked out a plea agreement to spare him prison time. But the penalty was devastating: three years of strict felony probation, five hundred hours of community service, and a permanent felony record that wiped out his remaining professional reputation in our town. My parents had to pull sixty thousand dollars out of my father’s private retirement account to pay for criminal defense attorneys and court restitution fees.
My mother tried calling me dozens of times. She left voicemails swinging wildly between furious accusations that I was an ungrateful daughter and desperate pleas to tell the judge that “it was all a misunderstanding.”
I never answered. I blocked her number, my father’s number, and Amanda’s number.
Last week, Arthur Vance invited Lily and me back to his office. He handed Lily an updated, certified statement from First Heritage Credit Union. The ninety-two thousand dollars was back in place, locked inside a newly restructured, court-monitored trust that required Arthur’s direct judicial sign-off for any future dispersal.
Lily looked at the total on the paper for a long moment. Then she looked up at me.
“Mom?” she asked softly.
“Yes, baby?”
“Dad really did leave this for me, didn’t he?”
“Every single cent,” I told her, kissing the top of her head. “Because you are his daughter, and you were always enough.”
For the first time in months, Lily smiled—a real, bright smile that reached her eyes.
My parents thought they could measure the worth of my child against the needs of my sister’s household. They thought grief made me weak, and that silence meant defeat. But when the dust settled, they learned the hardest lesson of all: you cannot steal a child’s future to build your own peace of mind, and family is not a license to commit a crime.