PART 1
My mother-in-law, Brenda, spent ten years telling anyone who would listen that I married her son for money.
She brought it up at our rehearsal dinner, making a joke about how a woman with a state clerical pension knows how to spot a rising software salesman. She brought it up at Thanksgiving dinners, at family cookouts, and whenever Greg bought me a birthday gift.
She liked to pat his arm, look across the room at me, and say, “Greg has always been generous with people who need taking care of.”
I never argued with her. I worked as a senior administrative coordinator for the county public works department. It was steady, unglamorous work, but it came with health insurance, a solid union pension, and a predictable schedule. Greg had the high-commission tech sales job. He drove the German sedan, wore the tailored suits, and loved picking up the tab when his mother wanted to go to the country club.
Then three months ago, Greg was laid off during a company-wide restructuring. His commission checks stopped overnight, and the severance package was barely two months of base salary.
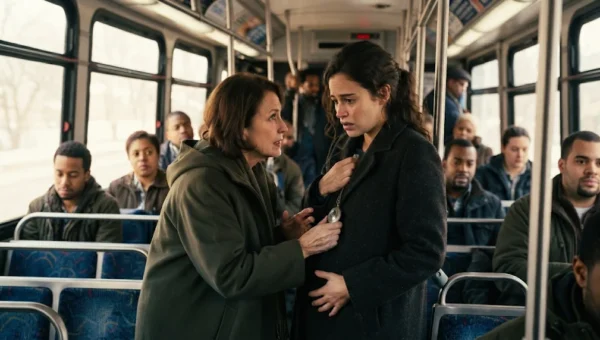
Brenda came over to our house the very next evening. She walked straight into my kitchen, poured herself a cup of decaf coffee, sat down at my table, and smiled across at me.
“Well, Karen,” Brenda said, her voice dripping with artificial sympathy. “Now we’ll see how long you stay.”
Greg was standing right by the refrigerator, holding a glass of ice water. He didn’t defend me. He didn’t tell his mother to stop. He just stared at the floor, looking like a man who expected me to pack a bag and leave because his income was gone.
I didn’t bother telling Brenda that I had been covering our nineteen-hundred-dollar mortgage payment out of my own direct deposit for the past six years.
Back when Greg’s company started having quarterly revenue dips, Greg had asked me to take over the house note so he could funnel his commission into an investment property downtown. I had agreed because I believed in our partnership. Every single month, my county paycheck covered the house, the property taxes, and the grocery bills, while Greg handled his car lease and his private investments.
I kept quiet because I loved my husband, and I didn’t need Brenda’s approval to know what I brought to the table. I just got up every morning at six, went to my office, and made sure our bills were paid on time.
To help offset his lost income, Greg had decided to put his downtown investment property on the market. It was a two-bedroom corner condo in the historic district that he had bought before we combined our banking accounts. Brenda had helped him pick it out seven years ago, and she constantly bragged about her son the real estate mogul.
The condo had gone under contract two weeks earlier to a cash buyer for three hundred and forty thousand dollars. The closing was scheduled for Friday morning, and the net proceeds were supposed to give Greg a comfortable safety net while he interviewed for new vice president roles.
Brenda had come over again on Wednesday afternoon to celebrate the pending sale. She brought a box of pastries from the bakery downtown and laid them out on my quartz counter.
“Once the condo closes, Greg can breathe,” Brenda said, licking sugar from her thumb. “He’s always known how to build wealth on his own. That’s Vance family blood for you.”
Greg sat at the table with his laptop open, checking his inbox.
Then his cell phone rang on the table. The screen showed the name of our closing realtor, Dan Miller.
Greg tapped the speakerphone button and leaned back in his chair. “Hey, Dan. All set for Friday morning?”
Dan’s voice came through the small speaker, sounding hesitant and strained. “Greg, I’m glad I caught you. We ran into a serious problem with the title search this morning. The title company can’t issue a clear deed for Friday.”
Greg frowned, sitting up straight. “What are you talking about? The title is clean. I bought that place outright through a private mortgage five years ago.”
“It’s not clean anymore,” Dan said. “A formal legal lien was recorded against the property at the county clerk’s office at eight-thirty this morning. An encumbrance for eighty-four thousand dollars.”
Brenda’s hand shot out, gripping the edge of my kitchen table so hard her rings clicked against the wood. “What? Who would dare file a lien against Greg’s condo? Who filed it?”
Dan paused on the line, the rustle of papers coming through the speaker. “The creditor on record is Karen Mitchell Vance.”
Greg slowly turned his head away from the phone, his eyes widening as he looked up and stared directly at me.
PART 2
The kitchen was so quiet I could hear the hum of the refrigerator motor.
Brenda looked at the phone, then turned her head toward me, her eyes bulging with disbelief.
“Karen?” Brenda’s voice rose into a shrill, furious pitch. “You put a lien on my son’s condo? Have you lost your mind? He needs that money to survive!”
Greg didn’t yell. His face had gone pale, the color draining from his cheeks down to his neck. He looked at me with a mixture of confusion and sudden dread.
“Karen,” Greg said, his voice barely above a whisper. “Why would you do that? You knew I was counting on this closing to bridge the gap until I found a new position.”
“Dan,” I said, leaning toward the phone on the table. “Did the title officer attach the certified judgment copy to the preliminary report?”
“Yes, Karen,” Dan answered from the speaker. “The filing includes the notarized promissory note from March 2018 and the recorded memorandum of debt. The title company cannot insure the transfer to the buyer until that eighty-four thousand is satisfied at the closing table, or until you sign a formal release.”
“Don’t you dare speak to her like she has any right to that money, Dan!” Brenda shouted, leaning over the table toward the speaker. “My son bought that condo with his own funds! She has no name on that deed! This is extortion! We will call the police!”
“Brenda, be quiet,” Greg snapped.
Brenda froze, her mouth hanging open. Greg had never spoken to his mother in that tone in his entire life.
“Dan, let me call you right back,” Greg said. He reached down with a shaking finger and disconnected the call.
He didn’t look at his mother. He kept his eyes locked on mine.
“You found the ledger,” Greg said quietly.
“I found the ledger two weeks ago, Greg,” I told him. My voice was calm and steady, without any anger in it. “When I went into your home office to find our tax returns for the mortgage renewal on this house.”
Brenda looked back and forth between us, her hands fluttering in agitation. “What ledger? Greg, what is she talking about? Tell her to sign the release right now! The buyers will walk if you don’t close on Friday!”
“She won’t sign it, Mom,” Greg said, his voice hollow. “Because I owe her every dime of that eighty-four thousand dollars.”
“You don’t owe her anything!” Brenda cried. “You’ve supported her for ten years! She’s been living in this house on your dime while you worked yourself into the ground!”
“Mom, stop it!” Greg shouted, standing up from his chair. The sudden force made his water glass tip over, spilling ice and cold water across the white quartz countertop. “She paid the mortgage! She has paid every single mortgage payment on this house for six years! Seventy-two payments at nineteen hundred dollars a month! That’s over one hundred and thirty-six thousand dollars of her salary that kept this roof over our heads while I took my money downtown!”
Brenda stepped back from the island, her face mottled with red blotches. She stared at Greg as if he had spoken in a foreign language.
“You told me you were paying it,” Brenda whispered. “You told me she was just helping with the cable and groceries.”
“I lied to you, Mom,” Greg said, looking down at the spilled water. “Because every time I told you Karen was carrying us, you made some cruel comment about her family or her job. You couldn’t stand the idea that your son wasn’t the big earner you bragged about at your bridge club.”
“That’s enough about the house, Greg,” I said, stepping between them. “Tell your mother what the eighty-four thousand dollars was actually for.”
PART 3
Greg closed his eyes. He leaned his hands against the edge of the kitchen counter, his shoulders slumping under his button-down shirt.
“Six years ago,” Greg began, his voice flat and worn out, “when I bought the condo, I told Karen it was an investment property for our future retirement. I told her we needed eighty-four thousand dollars in liquid cash to secure the commercial note without private mortgage insurance.”
“You took out a home equity line on this house,” Brenda said, trying to piece it together. “That’s standard practice.”
“No,” Greg said, opening his eyes and looking at his mother. “I didn’t take out a home equity line. The bank turned me down because my debt-to-income ratio was completely out of balance from leasing the two luxury cars and paying off credit cards from my first company that failed in Denver.”
Brenda blinked. “Your company in Denver didn’t fail. You sold your shares.”
“I lost forty thousand dollars in Denver, Mom,” Greg said bluntly. “I didn’t sell anything. I was buried in debt when I met Karen. The only reason the bank even considered our mortgage on this house was because Karen had twenty years of clean credit, a county job, and zero debt.”
Greg turned back to me, his eyes shiny with unshed tears.
“Karen went to her credit union in 2018,” Greg said. “She took out a personal loan against her supplemental municipal retirement savings. Eighty-four thousand dollars in cash. She handed it to me so I could close on the condo. We signed a promissory note in front of a notary at the credit union. I promised to pay her back with four percent interest within five years, or repay the full balance whenever the condo was sold.”
Brenda shook her head in stubborn refusal. “If you had an agreement, why did she wait until the week of the sale to file a lien? That’s vindictive, Karen! You’re trying to ruin him!”
“I didn’t file the lien to ruin him, Brenda,” I said, opening my leather tote bag on the table and pulling out a blue folder.
I laid two sheets of paper down on the dry section of the countertop.
“I filed the lien because two weeks ago, when I found the tax files, I also found the closing disclosure draft that Greg had prepared with Dan Miller,” I said.
I pointed to the disbursement section on the second page.
“Greg had the closing attorney set up the net proceeds distribution,” I said, looking directly at Brenda. “Two hundred and fifty-six thousand dollars in net cash after paying off the remaining bank balance. According to this instruction sheet, signed by Greg three weeks ago, one hundred and fifty thousand was being wired to an account named Vance Family Holdings LLC. An entity Greg set up with you last year, Brenda.”
Brenda’s mouth snapped shut. The righteous anger on her face evaporated into sheer panic.
“And the remaining one hundred and six thousand,” I continued, “was scheduled to be wired to a private brokerage account under Greg’s name alone. There was no line item for my eighty-four thousand dollars. There was no mention of the municipal retirement loan that has been deducting five hundred dollars from my paycheck every single month for six years.”
Greg lowered his head. He didn’t try to defend it.
“I was going to pay you back, Karen,” Greg whispered. “I swear I was. But Mom needed sixty thousand for her country club assessment and the repairs on her roof, and I thought if I put the rest into the market, I could double it before your retirement deadline next year.”
“You weren’t going to pay me back, Greg,” I said, my voice cutting through his excuses like cold steel. “You were going to let me retire at sixty-two with a reduced pension, while your mother lived comfortably on the money I earned working forty hours a week in a basement office.”
I looked at Brenda. For ten years, this woman had looked down her nose at my sensible shoes, my modest sedan, and my twenty-dollar haircuts. She had called me a gold digger at family dinners while secretly holding out her hand to take the very money my labor had secured.
“The lien stays on the property, Greg,” I told him. “When that condo closes on Friday morning, the title company will cut a certified cashier’s check directly to the county credit union for eighty-four thousand dollars, plus the accrued legal filing fees. Not one cent of the sale proceeds will be disbursed to your LLC until my retirement loan is satisfied in full.”
Brenda gripped her designer handbag against her stomach. “You can’t do this to us. Greg, tell her she can’t do this!”
“She can do it, Mom,” Greg said, his voice entirely defeated. “She has the signed promissory note. She has the bank transfer records. She owns the lien. If I fight her in court, the buyers will walk, the condo will sit on the market, and the bank will start foreclosure proceedings within ninety days because I can’t make the monthly carrying costs without a job.”
ENDING
The closing went through on Friday morning at ten o’clock.
We didn’t sit in the same room. I arrived at the title office at nine-forty-five, signed my creditor payoff authorization in a small conference room with Dan Miller, and watched the escrow officer execute the wire transfer.
Eighty-four thousand six hundred and twenty dollars was wired directly into my county credit union retirement account, completely wiping out the remaining balance on my personal loan and restoring my full supplemental pension fund.
Greg signed his seller documents thirty minutes later in an adjoining office. After my lien and the primary commercial lender were paid off, the remaining proceeds totaled a little over one hundred and seventy thousand dollars.
It was plenty of money to keep him afloat while he searched for work, but it wasn’t enough to fund his mother’s luxury lifestyle.
Brenda didn’t get her sixty thousand dollars for her country club dues or her roof repairs. She had to take out a reverse mortgage on her own suburban ranch house two months later to cover her debts. She hasn’t called our house since that Wednesday afternoon in my kitchen, and she hasn’t attended a single family dinner. For the first time in ten years, my holidays were completely free of her passive-aggressive jokes and cold stares.
The damage to my marriage was something money couldn’t fix.
When Greg came home from the closing on Friday afternoon, he tried to apologize. He sat on the living room sofa, crying, telling me that he had gotten trapped between his mother’s endless expectations and his own terror of looking like a failure. He offered to sign a postnuptial agreement giving me full ownership of our marital home.
I didn’t scream at him, and I didn’t throw plates. I simply told him that I couldn’t share a bed with a partner who viewed my life savings as a private slush fund for his family’s pride.
We separated three weeks later. Greg moved into a one-bedroom rental apartment near the interstate and accepted a mid-level sales management position at a regional logistics company. He is living within his actual means for the first time in his adult life.
I kept the house. Since my county salary had been paying the nineteen-hundred-dollar mortgage for six years anyway, my day-to-day budget didn’t change by a single dollar.
Last night, I sat down at my kitchen table after work with a mug of hot tea and my monthly credit union statement.
I opened the envelope and looked at the numbers printed in clean, crisp black ink.
My supplemental retirement balance was fully restored to its proper value. The loan balance showed zero. The house note was current, paid automatically from the checking account that bears only my name.
Beside my tea mug lay the small brass key to the front door deadbolt. I had hired a locksmith on Tuesday morning to replace the old cylinders, making sure that the only person who holds a key to this home is the woman who paid for it.
I took a slow sip of tea in the quiet kitchen, listening to the clock ticking on the wall, completely content in a life that nobody can ever claim I didn’t earn.