PART 1
I paid my parents more than $550,000 over eleven years for the four-bedroom house where my children took their first steps.
Back in 2013, my husband Mark and I had two toddlers, steady jobs, and terrible credit after a medical debt from my youngest child’s premature birth wrecked our scores. We found a sound colonial on Maple Ridge Road for $410,000.
When the bank turned down our loan application, my father, Arthur, stepped in with my mother at our kitchen table.
“We’ll buy it in our name,” Dad told us, tapping his knuckles on the tabletop. “We’ll carry the mortgage note. You pay us forty-two hundred dollars every month on the first. That covers the principal, the interest, the county taxes, and the hazard insurance. Every dollar above the baseline goes into your equity stake. When your credit clears up or the loan matures, we deed the house over to you. We are family. We help our own.”
There was no formal title deed drafted in our names, just my father’s word, a handshake, and my carbon copy checkbook. My father was a retired civil engineer who kept every receipt in metal file cabinets. I trusted him with my life.
For eleven years, forty-two hundred dollars left our account on the first of every month like clockwork. That came out to $554,400 paid directly to my parents.
Mark and I did not treat that house like tenants. When the roof leaked six years ago, we paid twelve thousand dollars out of pocket to reshingle it. When the furnace failed during a January blizzard, we replaced the heat pump for eighty-five hundred dollars. We remodeled the kitchen, planted hydrangeas along the front porch, and marked the children’s heights with pencil on the pantry doorframe.
By early this spring, our local housing market had exploded. Homes on Maple Ridge Road were selling within forty-eight hours, and a licensed appraisal on our property came back at nearly $800,000.
I called Dad to tell him Mark and I had finally qualified for a conventional mortgage to refinance the remaining balance and formally transfer the deed into our names.
Dad was quiet on the line for three seconds. Then his voice turned flat and brisk.
“We’re selling it, Karen,” Dad said.
I held the phone against my ear, thinking he had misunderstood. “Dad, we have the financing in place. We’re ready to buy out your remaining note.”
“You were never buying this house,” Dad said, his words coming out cold and sharp. “You were renting from us. The market is at the top, and your mother and I are cashing out our investment.”
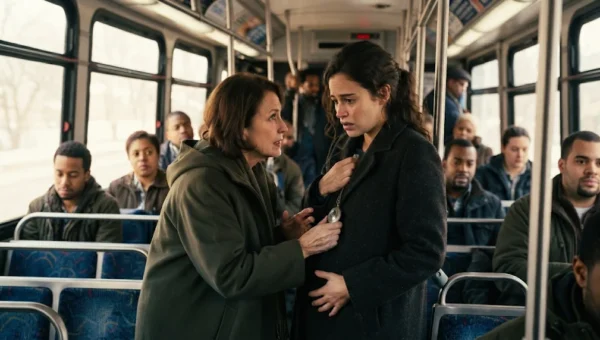
I thought he was bluffing. I thought he was having an old man’s bad day until Thursday afternoon, when a commercial real-estate agent in a beige blazer walked up my front steps with a lockbox and asked to schedule weekend open-house viewings.
I hired an attorney the next morning and filed an emergency injunction in county court to freeze the title and stop the sale.
Two weeks later, we stood in Courtroom 3B before Judge Miller. My parents sat on the opposite bench with an aggressive real-estate lawyer who argued that my payments were ordinary fair-market rent and that without a written land contract, the state property laws gave my parents absolute ownership of the $800,000 house.
Judge Miller listened in complete silence. He looked at my father’s bank deposits, then down at my cancelled checks.
Then the judge leaned over his bench, looked directly at my father, and asked one simple question: “Mr. Miller, if this was ordinary rent, why did you report these payments to the IRS as private mortgage interest income for eleven consecutive years?”
PART 2
The courtroom went dead silent.
My father’s lawyer froze with his hand resting on his legal pad. He slowly turned his head to look at Dad.
Dad did not speak. His face tightened into a gray, defensive mask, his fingers gripping the polished oak rail of the defense table. My mother, sitting beside him in her Sunday church coat, pulled her purse against her chest and looked down at her shoes.
Judge Miller did not wait for an answer. He turned to a thick manila folder resting on his center blotter.
“Counsel,” the judge said, his voice flat as a carpenter’s level, “prior to this hearing, plaintiff’s counsel subpoenaed your clients’ Schedule E and Schedule B tax filings for the years 2013 through 2023. On every single federal return, Mr. and Mrs. Miller reported forty-two hundred dollars a month from this property not as residential rental income, but as an installment land sale contract. They claimed the statutory depreciation was zero because the equitable ownership resided with the occupants, and they claimed the interest deduction as seller-financiers.”
Judge Miller looked over the top of his reading glasses right at my father.
“You cannot tell the Department of the Treasury for eleven years that you sold a house on contract to avoid rental tax penalties, and then walk into this courtroom and tell me these people were monthly tenants so you can pocket an eight-hundred-thousand-dollar windfall.”
My attorney, Robert Hayes, stepped up to the podium.
“Your Honor,” Robert said, “the plaintiffs have submitted fifty-four cancelled checks totaling over five hundred and fifty thousand dollars, along with documented receipts for twenty-four thousand dollars in structural capital improvements that no tenant would ever execute. The defendants took forty-two hundred dollars a month, paid their underlying twelve-hundred-dollar mortgage note, and treated the remainder as a private equity installment until the asset appreciated.”
Dad’s lawyer leaned over, whispering frantically into Dad’s ear. Dad waved his hand dismissively, his neck turning a dark, mottled red.
He stood up without being recognized by the court.
“That was my line of credit on that deed!” Dad barked, his voice echoing off the high plaster ceiling. “I put my neck on the line when her husband was broke! If the house went up in value, that belongs to the man whose name is on the bank note! She had eleven years of cheap living!”
“Mr. Miller, sit down,” Judge Miller warned, his gavel tapping the wooden block once with a sharp, heavy crack. “You are one word away from a contempt citation.”
Dad sat down heavily, his jaw working silently.
“I am issuing an immediate preliminary injunction against the sale or transfer of this property,” the judge ordered. “The notice of lis pendens remains attached to the title. Both parties will submit to mandatory forensic accounting within thirty days, and we will reconvene for a final decree of equitable trust.”
We walked out of the courtroom into the marble hallway.
Mark had his arm wrapped tight around my shoulder, his hand steady against my back. My knees were shaking so hard I had to stop beside the water fountain.
Behind us, the heavy oak courtroom doors swung open.
Dad came marching out, his coat unbuttoned, his face dark with fury. My mother trailed three paces behind him, dabbing her eyes with a crumpled tissue.
Dad stopped four feet from me, pointing an index finger straight at my chest.
“You dragged your own parents into open court,” Dad hissed, his voice trembling with venom. “You humiliated us in front of a county judge over money.”
“You tried to sell the roof over your grandchildren’s heads, Dad,” I told him, looking him dead in the eye. “You took fifty thousand dollars a year from my family, and you tried to throw us onto the sidewalk for a profit.”
“We gave you a roof when nobody else would touch you!” he shouted, loud enough that a bailiff near the elevators looked over. “You think you’re clever because your lawyer found some tax schedules? You won’t see a single dime of that equity when this is through. I will let the bank foreclose on the note before I hand you that deed.”
“Arthur, stop,” my mother whispered, catching his sleeve with both hands. “Please, Arthur. Don’t say that.”
Dad yanked his arm free, turned on his heel, and stormed toward the revolving doors.
PART 3
The following four weeks were a quiet war fought through accountant spreadsheets and registered letters.
Robert Hayes hired a certified forensic auditor to review the entire eleven-year payment history. The paper trail was devastating.
My parents had bought the Maple Ridge Road house in 2013 for $410,000, putting eighty thousand dollars down from their personal retirement funds and taking out a thirty-year fixed mortgage for $330,000 at 3.8 percent interest. Their monthly payment to the bank for principal and interest was $1,536. County property taxes and insurance added another $620, bringing their total monthly carrying cost to $2,156.
Every month, Mark and I had handed them $4,200.
That meant my parents had pocketed $2,044 in pure surplus every single month for one hundred and thirty-two consecutive months. Over eleven years, they had accumulated $269,808 in cash from our payments above the actual cost of the home, while our payments paid down their mortgage principal from $330,000 to just $198,000.
The auditor laid the numbers out on a single summary chart.
Mark and I had not just paid for our housing. We had handed my parents over a quarter of a million dollars in profit while paying off more than half of their bank loan.
And now that the house was appraised at $795,000, Dad wanted to sell the property, pay off the remaining $198,000 mortgage, and walk away with nearly six hundred thousand dollars in tax-free profit, leaving Mark, our children, and me with zero.
The reason for Dad’s sudden greed finally came to light three days before our second court date.
My younger brother, Scott, was thirty-six, lived two states away, and had spent ten years hopping from one failed commercial startup to another. In February, Scott had convinced my father to invest in a commercial car-wash development outside Charlotte that needed four hundred thousand dollars in immediate liquid capital. Dad had already drained his own retirement savings to back Scott’s earlier ventures, and the Maple Ridge house was the only major asset he had left to tap.
Dad wasn’t selling the house because he thought we were tenants. He was selling the house because he had promised our equity to bail out his favorite child.
On a rainy Tuesday morning in June, we returned to Courtroom 3B for the final hearing.
This time, Dad did not shout. He sat beside his attorney with his shoulders hunched, staring at the forensic audit report laid out on his desk. His attorney looked exhausted, having spent the previous week reviewing the federal tax transcripts that proved my father had treated the transaction as an equitable sale from day one.
Judge Miller did not take more than twenty minutes to deliver his ruling.
“Under the doctrine of equitable conversion and partial performance,” the judge stated, his voice ringing through the quiet room, “the court finds that an enforceable oral contract for the sale of real property existed between the parties, ratified by eleven years of continuous payment, substantial capital improvement, and consistent federal tax reporting by the defendants.”
Judge Miller adjusted his glasses and looked down from the bench.
“The court hereby imposes a constructive trust upon the property at 4180 Maple Ridge Road for the benefit of the plaintiffs. The court orders the defendants to execute a warranty deed transferring full fee-simple title to the plaintiffs within twenty-one days.”
The judge then turned to the financial reckoning.
“The plaintiffs will tender to the defendants the sum of $198,420, representing the exact payoff balance of the underlying commercial mortgage. However, against that balance, the court credits the plaintiffs sixty-two thousand dollars for capital preservation expenses and tax overpayments collected by the defendants without lawful accounting. The net buyout sum required from the plaintiffs to clear the title is hereby set at $136,420.”
Dad’s head dropped onto his chest.
He didn’t get his six hundred thousand dollar windfall. He didn’t get to fund the car-wash project in Charlotte. By trying to rob his daughter of an eight-hundred-thousand-dollar home, he walked away with less than a third of the cash he had planned to seize, while his tax returns were referred to the state revenue department for audit review.
Judge Miller brought his gavel down with one clean, final strike.
“This court is adjourned.”
ENDING
The closing took place twenty days later in a quiet title office on Market Street.
Dad did not attend in person. He sent his attorney with a limited power of attorney to sign the warranty deed. My mother came alone, sitting in the corner of the waiting room with her hands folded in her lap, looking at the floor while the notary stamped the transfer sheets.
Mark and I signed our new loan papers, wired the $136,420 court-ordered payoff through our credit union, and received the recorded deed.
When the notary gathered her stamp and left the conference room, I walked over to the chair where my mother was sitting.
I reached out and handed her the duplicate set of house keys she had kept on her ring for eleven years.
“Here, Mom,” I said gently.
My mother looked up, her eyes rimmed with red. Her chin trembled violently as she looked at the brass keys in my palm.
“Karen,” she whispered, her voice cracking. “Your father was only trying to make sure everyone had something. Scott was in so much trouble with those lenders.”
“Dad didn’t try to make sure everyone had something, Mom,” I told her. “Dad tried to take the shoes off my children’s feet to put them on Scott’s. You let him do it. You sat in that kitchen every Sunday and ate our food while you knew what he was planning.”
She didn’t take the keys. She wiped a tear from her cheek with her finger, stood up slowly, and walked out the glass doors into the parking lot without looking back.
I walked out to our car, where Mark was waiting with the windows down, the warm June breeze blowing through the trees.
We drove back to Maple Ridge Road.
The kids were out in the front yard with our dog, throwing a tennis ball across the green grass. The hydrangeas along the porch were full and blooming blue in the summer sun.
I walked up the porch steps, ran my hand along the painted railing that Mark and I had bolted into the concrete, and opened the front screen door.
Inside, the house smelled of lemon wax, clean laundry, and cedar.
I walked over to the kitchen pantry, pulled open the door, and looked at the faint pencil marks on the pine frame showing my son’s height from when he was three years old, up to the notch we made on his fourteenth birthday last month.
I rested my fingertips against the wood, feeling the solid grain beneath the paint.
We had paid for every single inch of this floor with eleven years of honest sweat, and there was no contract in the world strong enough to take it away from us again.