PART 1
The white envelope from the Hamilton County Auditor arrived on a Tuesday afternoon in late September. It was addressed to both of us, but Evelyn had not checked the mailbox yet because she was at her Tuesday yoga class.
I almost left it on the kitchen counter next to the grocery coupons. For twenty-four years, Evelyn had handled our household paperwork.
She had the logins, the spreadsheets, and the digital filing folders on her laptop. Whenever I offered to sit down on a Sunday to balance our accounts, she would wave her hand and tell me to focus on my lesson plans. I teach high school biology, and between grading lab reports and prepping AP exams, I was always tired enough to accept the favor.
I opened the letter with a butter knife because the seal was already coming loose.
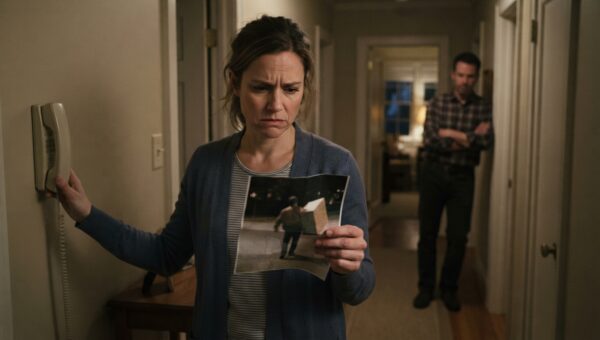
Inside was a single printed form with a yellow warning band across the top. It was an automated notice regarding our owner-occupancy homestead credit. The county indexing system had flagged an inconsistency: our primary tax identification was linked to a newly registered residential parcel seventy miles east, near Rocky Fork Lake.
The letter stated that the county could not apply primary residence tax exemptions to two separate properties under the same household identification.
I read the parcel number three times. We did not own a second property.
For the past three years, Evelyn had insisted we needed to cut back on everything. When my ten-year-old sedan started making a rattling noise in the transmission last spring, she told me we could not afford the repair, so I started packing peanut butter sandwiches for lunch and riding the suburban bus to school three days a week. We had postponed replacing our drafty front windows. She told me our joint retirement supplement was falling short because the market was sluggish.
I took the letter into her small home office off the hallway. Her desk was neat, arranged with matching acrylic organizers and brass paper clips. I was looking for our latest property tax receipt to see if the auditor had made a simple clerical error with our social security numbers.
In the second drawer, behind a folder of church donation receipts, I found a pale green envelope.
It was a utility bill from South Central Power Company. The service address was a lakefront drive in Highland County.
The account was in Evelyn’s name. The bill was for $142, and the payment stub showed an automatic debit from an account number I did not recognize.
I sat in her desk chair with the two pieces of paper in my hands. The grandfather clock in the hall ticked steadily. Evelyn was due home in forty minutes, and for the first time in twenty-four years of marriage, I realized I did not know what was happening to our money.
PART 2
I did not ask Evelyn about the letter that evening. When she walked in carrying her gym bag, complaining about traffic on Montgomery Road, I folded the tax notice and the electric bill and slipped them into my school briefcase.
“Did the mail come?” she asked, dropping her keys into the ceramic bowl by the door.
“Just flyers,” I said. My voice sounded flat to my own ears, but she did not notice. She was already scrolling through her phone.
The next morning, I took a personal day from school. Instead of driving to the high school, I went straight to the downtown branch of Fifth Third Bank, where we had maintained our checking account and our home equity line of credit for nearly two decades.
I asked to speak with a branch officer and provided my driver’s license. The representative, a quiet man named Miller, pulled up our joint profile on his monitor.
“I need a complete transaction history for our home equity line over the last eighteen months,” I said.
Mr. Miller clicked through several screens, then adjusted his glasses. “You are looking for the draws authorized through the online portal?”
“All of them,” I said.
He printed a six-page ledger and slid it across the mahogany desk.
Between March of last year and June of this year, three separate large transfers had been pulled from our equity line. The amounts were $65,000, $80,000, and $73,400. Together with five thousand dollars drawn from our liquid rainy-day savings, the total came to exactly $218,400.
Every single transfer had been routed to an entity called Heron Point Holdings LLC.
“Mr. Miller,” I said, pointing to the authorizations, “these show an electronic signature under my name. Did the bank send a confirmation code to my phone?”
He checked the authentication log. “The two-factor authentication was routed to the primary mobile number on file, ending in 4108.”
That was Evelyn’s cell phone. My phone had never received an alert.
From the bank, I drove directly to the county recorder’s office in Hillsboro, near the lake. I paid four dollars for certified copies of the deed, the mortgage filing, and the title insurance policy for the parcel listed on the tax notice.
The documents were clear and cold. The property was a three-bedroom lakefront condominium. The title insurance policy and the county recording identified the buyer as Evelyn Miller, “a single woman acquiring sole separate property.”
She had used our home equity, built over twenty-four years of my teaching salary and shared scrimping, to buy herself a luxury retreat while claiming we were nearly broke.
I did not go home. I sat in a diner parking lot with the engine idling and called a forensic family attorney in Cincinnati whose name had been recommended by a colleague two years ago.
By two o’clock, I was sitting in the attorney’s office on Walnut Street. Her name was Sarah Vance. She reviewed the certified deeds, the bank ledgers, and the tax notice without looking up for twenty minutes.
“This is not just marital asset dissipation,” Sarah said, setting her pen down. “This is unauthorized borrowing using forged electronic credentials. We are going to notify the bank’s fraud division immediately to freeze the remaining credit line, and we are filing an emergency motion for legal separation with a temporary restraining order to prevent her from transferring, selling, or encumbering that lake property.”
“Can she sell it out from under us before the court steps in?” I asked.
“Not after tomorrow morning,” Sarah replied. “We file at eight-thirty. Then we sit down with her.”
PART 3
Two days later, Evelyn walked into Sarah Vance’s conference room.
She had dressed in her good navy blazer, the one she wore to school board meetings and family graduations. When she first received the formal notice of representation, she had tried calling my phone twenty times in two hours, alternating between tears and fury, demanding to know why I had locked our joint accounts. I had not answered. I had texted her a single sentence: “We will talk in my attorney’s office on Friday morning.”
Evelyn sat across the polished table from me. Her hands were gripping her leather handbag.
“Brian, this is ridiculous,” she began, looking directly at me and ignoring Sarah. “You are embarrassing both of us over a simple misunderstanding. I was setting up an investment for our retirement. Real estate near the lake is appreciating faster than index funds. I was trying to build equity for our future.”
Sarah opened a manila folder and slid three documents across the table.
“Mrs. Miller,” Sarah said calmly. “You took out $218,400 from your husband’s joint equity line without his knowledge or lawful consent. You used his electronic signature without his authorization. And you titled the property not in a joint trust, but in a private LLC where you are listed as the sole managing member, under a title deed that declares you as a single woman.”
Evelyn looked at the title document. The color drained from her face, but she did not apologize.
“You don’t understand what it feels like,” Evelyn said, her voice dropping into a tight, sharp whisper. “Our kids are gone. You’re content to grade papers, rake leaves, and retire in that drafty house until we die. I am fifty years old, Brian. I spent twenty-four years taking care of everyone else. I wanted something that was entirely mine. Something with prestige. Something that didn’t depend on your permission or your teacher’s pension.”
“You took $218,400 from our home,” I said. My voice did not shake. “While you were buying custom tile for a lakefront patio, you told me we couldn’t afford seven hundred dollars to fix my car transmission. I took the bus for eight months so you could pay the electric bill on a condo where you planned to live without me.”
She looked down at her hands. “It wasn’t like that.”
“It is exactly like that on paper,” Sarah Vance intervened. “And the paper is what the magistrate will see on Monday. Here are the terms. You will sign an immediate agreed order listing the Highland County condominium for sale with a court-approved broker. Every dollar of net proceeds will be wired directly into an escrow account to fully satisfy and pay off the $218,400 lien against the marital residence. You will pay all broker fees, transfer taxes, and legal expenses out of your separate share of marital assets. In exchange, Mr. Miller will waive formal referral of the electronic signature fraud to the county prosecutor.”
Evelyn stared at the settlement agreement. The arrogance was gone, replaced by the reality of what she had signed and what the court record would show to her family and friends.
“And what happens to our house?” she asked quietly.
“I keep the house,” I said. “You will sign the quitclaim deed as part of the structured separation.”
She picked up the pen. Her signature was slow and careful. It was the same signature she had placed on the secret deed six months earlier, but this time it restored what she had taken.
ENDING
The lakefront condominium sold five weeks later to an out-of-town buyer.
Because the real estate market was still active, the sale generated enough cash to pay off the entire $218,400 fraudulent balance on our home equity line, clear the closing costs, and pay Sarah Vance’s legal fees. Evelyn had to draw six thousand dollars from her individual inheritance savings to cover the remaining tax penalties.
The structured financial separation was finalized just before Thanksgiving. Evelyn moved into an apartment in Hyde Park. We do not speak except through short, necessary emails regarding our adult children’s schedules.
The primary house in Cincinnati is quiet now. I took out a small, sensible home improvement loan under my name alone and replaced all eleven drafty windows on the first floor. I had the transmission in my car rebuilt at a local shop down on Beechmont Avenue.
This morning, the first real chill of November settled over the Ohio River valley. I made a pot of black coffee and carried a mug out to the back porch.
I opened my laptop and checked my personal checking account. The balance was modest, but every dollar was accounted for, every login belonged to me, and the lien on my roof was gone. I closed the screen, leaned back in the wicker chair, and listened to the dry maple leaves scraping across the lawn in the quiet morning air.